


With changing viewing habits putting pressure on distribution, the sector is looking to YouTube and FAST channels as a means to monetise existing content and deliver straight to consumers. But do the numbers add up?
One of the biggest shifts in distribution strategy over recent years has been the increasing propensity for rights holders to go direct to consumer. As this year’s Distributor Survey findings indicate, the effect of changing viewing habits on the streamer and broadcast ecosystems is putting ever increasing pressure onto the distribution sector, whether that’s a squeeze on pipeline, client activity or the level of deficit funding required to get shows off the ground.
But one area of clear growth is in the direct-to-consumer (DTC) market. For many this means YouTube, and the Google-owned service has been on something of a publicity push over the past 18 months as it looks to position itself as the aggregator of choice – not only as a platform through which viewers can access the niche content they crave but as a delivery mechanism for rights holders.
Results are mixed when it comes to how much revenue YouTube is actually delivering. A third of respondents say YouTube accounted for 11%-24% of their total revenues over the past year, but the majority put the figure at 0%-10%.
However, the trajectory is clear – almost all respondents in this year’s survey say they expect YouTube to become “a significant partner” in the exploitation of long-form programming over the next 12 months, and companies are planning accordingly.
BBC Studios chief executive of global content and chief creative officer Zai Bennett points to the fact that his company has started reporting the contribution it is seeing from social video, which he says reflects “the reality that viewers increasingly engage with content across a much wider ecosystem”.
More broadly, he says the growing number of ways viewers can consume content are all monetisation points now, meaning scripted and unscripted IP can have “multiple lives”. “It might launch on a broadcaster, find a new audience on a streaming platform, then continue to be discovered through social clips or FAST channels,” he says. “These opportunities just didn’t exist at the same scale 10 years ago.”
Fremantle was among the first distributors to embrace YouTube, launching gameshow network Buzzr more than a decade ago, and commercial chief Jens Richter says entertainment continues to provide returns.
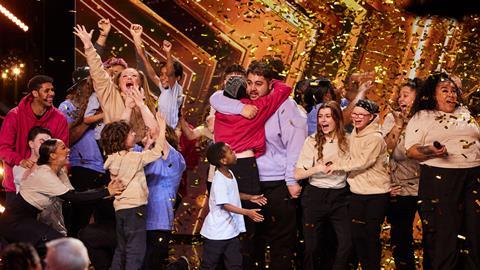
“We have found those formats lend themselves to the platform and help strengthen a brand’s visibility,” he explains, highlighting Britain’s Got Talent’s golden-buzzer moments, while iconic brands such as the original Baywatch series are available on YouTube, with viewers in almost every country, he says.
Growth strategy
Cineflix Rights is also expanding its YouTube activity, which already counts more than 20 channels in operation. Chief executive Tim Mutimer says the company is starting to work closely with in-house and third-party producers to expand its IP on YouTube through original production for the platform, a move that fi ve years ago might have seemed far-fetched.
It is not only bigger groups that are finding success, either. Karen Young, founder and chief executive of Orange Smarty, which sells shows such as A Place In The Sun, is clear that YouTube is playing a central role in her growth strategy. “We’ve had an accelerated digital strategy for a number of years, but the past 12 months has seen a significant return on revenues,” she says.
Orange Smarty works with partners to deliver IP across platforms, including through its own YouTube channels, but Young adds that early adoption and an understanding of rights management and windowing strategies have been key, particularly the need to take a longer view when it comes to monetising content.
Although unscripted has traditionally been seen as the bread and butter of YouTube consumption, Eccho Rights is also finding success with its scripted library. “For premium first-run drama, exclusive broadcaster and SVoD windows still hold the primary value,” says Handan Özkubat, director of Turkish drama.
“But for library and long-running catalogue, YouTube has become a genuine revenue window – one we are already exploiting at scale through Klik Studios rather than treating as a future opportunity.”
While YouTube – even after taking its roughly 40% cut – is providing meaningful returns, respondents also suggest FAST remains an opportunity. Some markets, particularly across Europe, have been slower in the uptake, but growth in the US means many rights holders continue to see rising returns. Indeed, 70% of respondents report FAST revenues increasing over the past 12 months.
Fremantle is also utilising its IP across more DTC spaces than ever, with a significant increase in the volume of content published on AVoD and other ad-supported platforms. Richter highlights that its FAST channels alone have generated more than half a billion hours of video consumption in the past year, while Mutimer says FAST, along with its broader digital distribution business, is a key part of his commercial strategy.
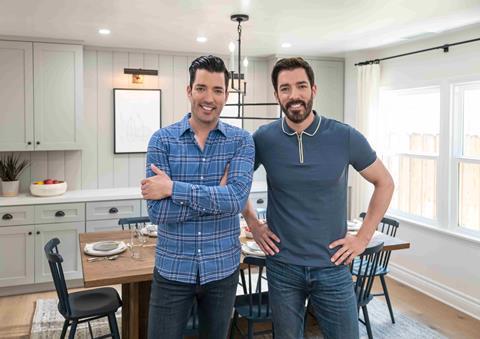
Cineflix has seen double-digit percentage revenue growth from this activity over the past year, he continues, with further growth pencilled in as DTC rollouts of major brands such as Property Brothers, Mayday: Air Disaster and Château DIY deliver via owned channels and third parties. The growth of these more nascent platforms is also providing new opportunities, such as the decision to invest in Barcelona-based Love TV Channels.
As part of the deal, Cineflix delivers localised versions of its franchises for its thematic TV channels in 34 countries, while receiving a stake in their business in return. “We are also exploring a partnership with a producer and a world-famous institution in Australia to provide YouTube channel content,” he adds.
BBC Studios sees FAST as a complementary tool “to engage fans”, while also introducing library shows to new audiences, and Bennett adds that it provides insight into audience demand for specific genres and franchises.
But its value to niche distributors remains questionable. Koulla Anastasi, managing director of Woodcut International, says it has “relatively conservative estimates” on sales growth, and Parade Media chief Matthew Ashcroft says he is taking a targeted approach to focus on North America, where the biggest opportunity is around single-IP channels built on established property brands.
“For us, FAST is another way to extend the lifecycle of premium content, grow audience reach and create recurring ad revenue, while strengthening the long-term value of our IP,” he says.
While YouTube and FAST are seen as revenue raisers, questions around the value of social media to distributors remain. Richter highlights the growth of Fremantle’s social output, which drove more than 55 billion views in 2025. Such engagement stats might be difficult to comprehend but the direct revenue they are driving also remains difficult to pinpoint.
“Social platforms help audiences discover content, but they’re also becoming meaningful standalone commercial opportunities”
Jens Richter, Fremantle
Richter, however, says the value is more around building a DTC relationship around a show brand, while Bennett says revenues are growing. “Social platforms help audiences discover content and build awareness around our brands, but they’re also becoming meaningful standalone commercial opportunities,” he explains.
“We’ll follow the audience, find the right way to engage them and create value from our content.” He caveats that this shift doesn’t replace broadcasters or streamers, “but does afford us another layer to generate returns over time”.
Of course, streamer and broadcaster deals remain the major revenue driver for distributors, but more nascent platforms are providing meaningful returns. Cineflix’s YouTube strategy is focused on providing full episodes supported by clips, shorts and live streams, and Mutimer says some AVoD revenue-share performances are now starting to emulate what the company would get on second window fees – “and in some cases, it exceeds that”.
No doubt, then, as to why it is planning on doubling the number of channels it operates over the next couple of years. Windowing of content is also increasingly a central piece of the digital strategy from the get-go, adds Woodcut’s Anastasi, while Espresso Media International managing director David Hooper says AVoD revenues could account for 50% of his revenues within three years.
For ITV Studios president of global content Ruth Berry, the “ongoing growth” across AVoD and YouTube has been the most significant development over the past 12 months. And she’s not alone: more than a third of respondents point to AVoD as the biggest development over the past year, with Parade’s Ashcroft describing YouTube as a destination to “grow loyal audiences, generate meaningful ad revenue and create new opportunities for brand partnerships.”
The Google-owned platform might continue to divide opinion on its long-term effect on the production landscape, but for rights holders looking to monetise existing content, the direction of travel is clear.
BBC Studios retains top spot as rivals stumble
Market leader bucks trend with 20% revenue rise while biggest competitors all report declines
- 1
 Currently
reading
Distributors Survey 2026: Distributors take the direct route
- 3
- 4


No comments yet